Shares of The Boeing Company dropped almost 10 percent to an 18-month low on Tuesday after leadership warned investors that the industrial ramp-up of its bestselling 737 Max jetliner faces another prolonged delay. Rather than achieving a steady assembly rate of 47 narrow-body aircraft per month this year, the planemaker disclosed it will not reach that threshold until early 2027, severely curtailing near-term deliveries and dismantling previous financial turnaround projections[1].
The disclosure, delivered alongside third-quarter financial results and detailed by executives on Tuesday morning, caught Wall Street off guard. By deferring the output increase, Boeing confirmed it will miss its long-standing goal of delivering roughly 500 commercial aircraft this year. In turn, the company slashed its free cash flow guidance for both 2027 and 2028, sparking an aggressive market selloff that overshadowed narrow quarterly operating gains and certifications for newer aircraft variants[1].
Production Bottlenecks Push Targets Into 2027
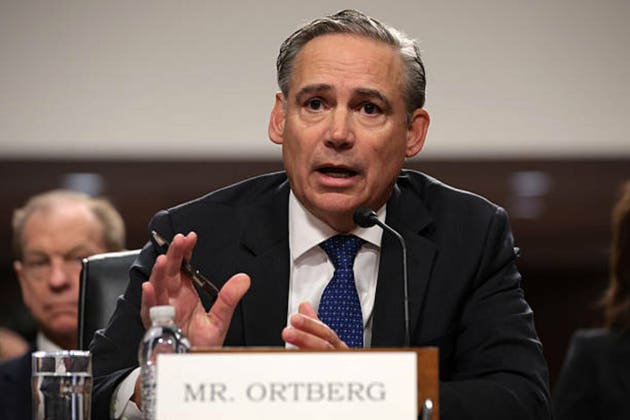
Speaking in an interview with CNBC and addressing analysts on the quarterly earnings call, Boeing Chief Executive Kelly Ortberg conceded that stabilizing manufacturing lines at the company's Renton, Washington facility is taking significantly longer than anticipated. Boeing had previously targeted reaching 47 aircraft per month by summer 2026, up from an operating pace hovering around 41 planes per month. Ortberg stated that line stabilization will now extend into early next year, leaving any push toward 52 aircraft per month delayed until the second half of 2027.
Chief Financial Officer Jay Malave told analysts that wing manufacturing constraints remain the most persistent structural bottleneck in Renton. The company has struggled to fabricate wings fast enough to feed the final assembly line without sacrificing assembly precision. Rather than forcing unfinished work down the line, an operational misstep that led to intense regulatory scrutiny and quality failures in previous years, Ortberg emphasized that the company is deliberately slowing the ramp to protect assembly standards[1].
We are ramping up aircraft, and we're doing that in the right way.
Kelly Ortberg, Chief Executive Officer, Boeing
Ortberg noted in an employee memo that although Boeing is operating on a firmer operational footing than it was twelve months ago, the manufacturing division still has considerable work ahead to stabilize execution across suppliers and factory floors.
Financial Impact and Cash Flow Shortfalls
The slower assembly timeline directly compresses Boeing's cash generation, because planemakers collect the vast majority of aircraft purchase funds only upon final delivery to airline customers. Boeing informed investors that it now expects to generate approximately $3 billion in free cash flow in 2027 and roughly $6 billion in 2028. Those internal estimates fall well short of Wall Street expectations; consensus numbers compiled by LSEG had projected $5.6 billion in free cash flow for 2027 and $9.6 billion in 2028.
The revised guidance triggered widespread equity downgrades and selling. Boeing stock dropped 9.6 percent to finish at $170.23, marking its sharpest single-day retreat since April 2025 and wiping billions off its market capitalization. As Reuters reported, market participants were quick to penalize the multi-year delay in capital return, especially given the heavy debt load Boeing accumulated while navigating successive quality crises[3] [8].
| Metric | Current Guidance / Actual | Wall Street Consensus / Previous Goal |
|---|---|---|
| 737 Max Output (47/month) | Early 2027 | Summer 2026 |
| Full-Year Jet Deliveries | Below 500 | Approx. 500 units |
| 2027 Free Cash Flow | ~$3.0 billion | ~$5.6 billion (LSEG) |
| 2028 Free Cash Flow | ~$6.0 billion | ~$9.6 billion (LSEG) |
| Q3 Adjusted EPS | -$0.34 loss per share | -$0.21 loss per share |
For the third quarter, Boeing reported a core loss of 34 cents per share, wider than the 21-cent loss projected by analysts tracked by LSEG. Total revenue rose 4 percent year-over-year to $24.19 billion. Within that total, the Commercial Airplanes division generated $10.7 billion in revenue, down 3 percent, while logging an operating loss of $697 million. Management cited higher production expenses, less profitable delivery mixes, and lingering supply disruption for the commercial unit's wider losses[9].

Backlog and Defense Strength vs Delivery Reality
The manufacturing delay highlights a widening paradox across Boeing's balance sheet: strong secular demand for commercial aerospace hardware coupled with an inability to translate that demand into immediate revenue. Boeing ended the third quarter with an all-time high company backlog of $745 billion, booking 300 net commercial orders during the period from carriers including Lufthansa, Ethiopian Airlines, and Turkish Airlines.
The company also achieved key regulatory milestones that had languished for years. The Federal Aviation Administration cleared amended type certification for the smaller 737 Max 7 during the third quarter, followed by formal certification for the high-capacity 737 Max 10 in October. However, without factory floor stability and adequate engine and component availability, certification progress offers little immediate financial relief if planes cannot roll out of hangars at pace[5].
Offsetting commercial headwinds, Boeing's Defense, Space & Security segment reported a noticeable operational recovery. Defense revenue rose 15 percent to $7.9 billion, posting nearly $500 million in quarterly operating earnings supported by improved operational margins and a $252 million subsidiary sale. Boeing also captured the U.S. Navy contract to design and construct the sixth-generation F/A-XX carrier fighter, expanding defense order backlogs to a record $101 billion.
Execution Credibility Remains the Core Headwind
While demand fundamentals remain secure because Boeing operates in an effective global duopoly with European rival Airbus, institutional confidence rests entirely on manufacturing discipline. Analysts noted that airlines worldwide are clamoring for narrow-body aircraft amid elevated travel volume and high fuel prices, which heighten the necessity of fuel-efficient single-aisle jets. Yet every quarter of delayed output cedes operational ground and market share to Airbus's competing A320neo family.
Ortberg has adamantly told investors that Boeing will not sacrifice quality controls to hit arbitrary delivery milestones, an approach designed to placate regulators and restore systemic integrity. However, as Tuesday's share plunge demonstrated, Wall Street patience is wearing thin. Until factory operations can reliably solve wing fabrication and assembly line bottlenecks, Boeing's path to robust free cash flow and balance sheet restoration will remain stuck in a holding pattern[1].
Video
Wing Production Lag Plagues Boeing’s Hopes To Boost 737 MAX Output To As Many As 63 Monthly Jets →